Quantitative Insights
Independent fundamental valuations, DCF intrinsic models, and thematic research covering Quantitative Insights.
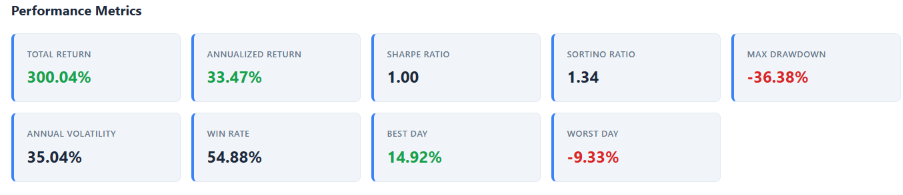
Momentum Omega: the long-only backtest returned 35% a year. $100K grown to $400K in 4 years
Momentum Omega’s long-only Scenario D1 grew $100,000 to $400,039 in 2022–2026 (33.5% a year, Sharpe 1.00), with a maximum drawdown of −36.4%. The returns are before slippage and carry no benchmark, and seven of today’s ten holdings are AI hardware or memory names.
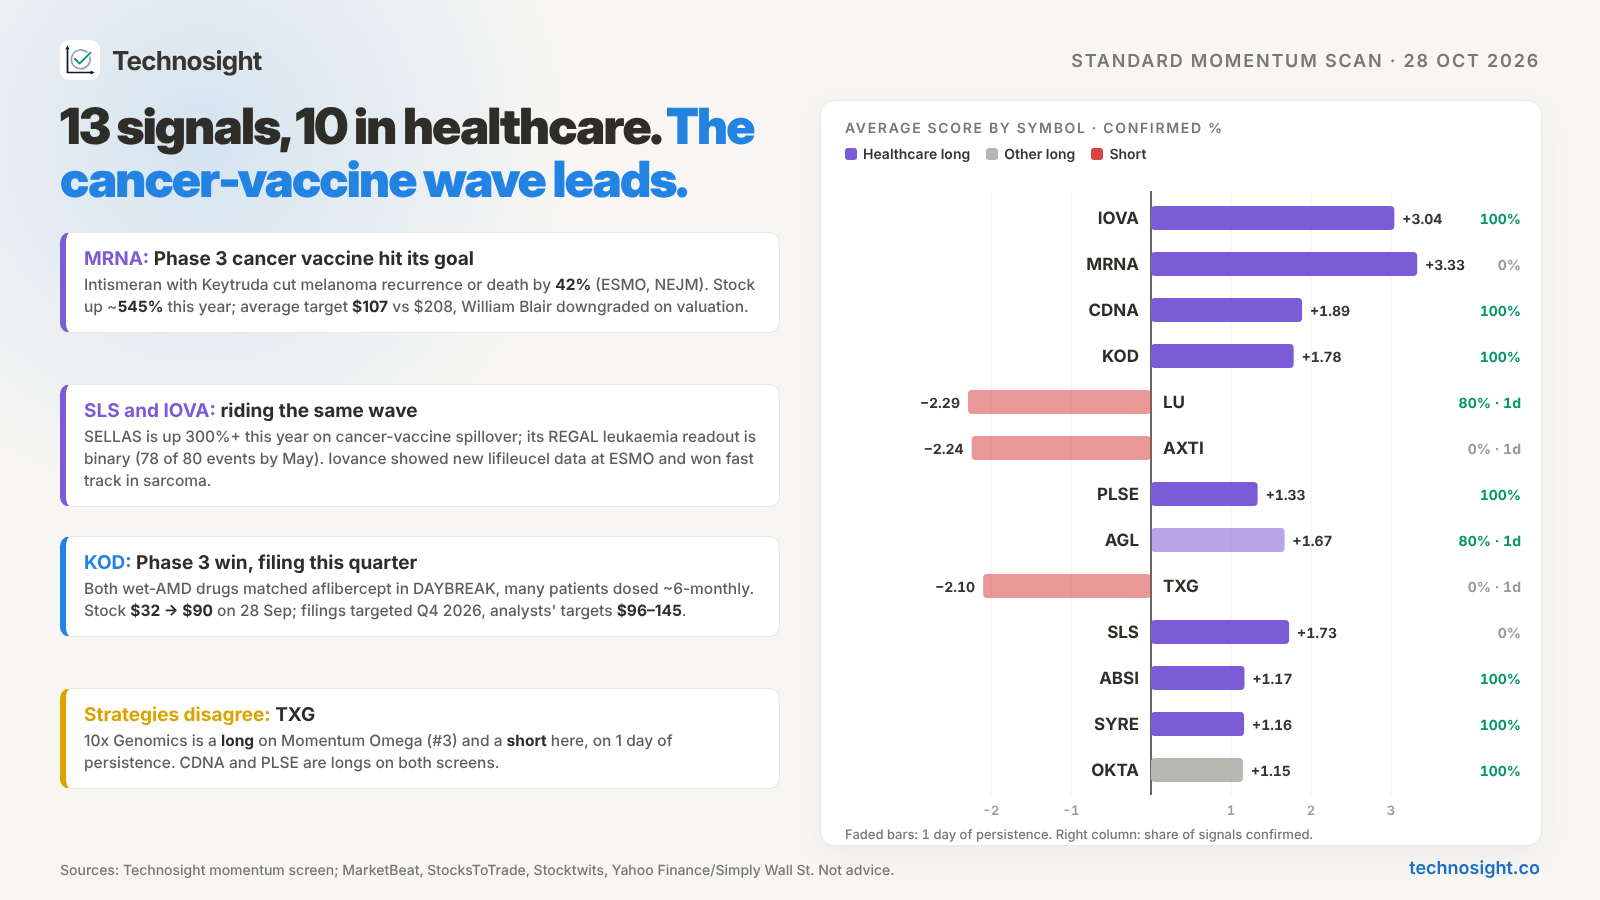
Six quant strategies, 2,000+ stocks a day: what the screens flagged this week
Every day we scan more than 2,000 US stocks with six quant strategies: momentum, volatility-adjusted momentum, mean reversion, statistical arbitrage, trend following and volatility breakout. A signal is a starting point; the research behind it decides whether it’s worth acting on. This week the momentum screens were led by healthcare, with Moderna’s Phase 3 cancer-vaccine win lifting SELLAS and Iovance alongside it, and Kodiak re-rating on Phase 3 eye-drug data. Volatility-adjusted momentum picked up Dell’s $95B AI server backlog. Mean reversion flagged five cybersecurity names as one stretched trade, and showed why every signal needs checking: one short was a takeover target, and one long was cheap because the company had withdrawn guidance. Below are examples from three of the strategies. Full lists, scores and the remaining strategies are for subscribers.
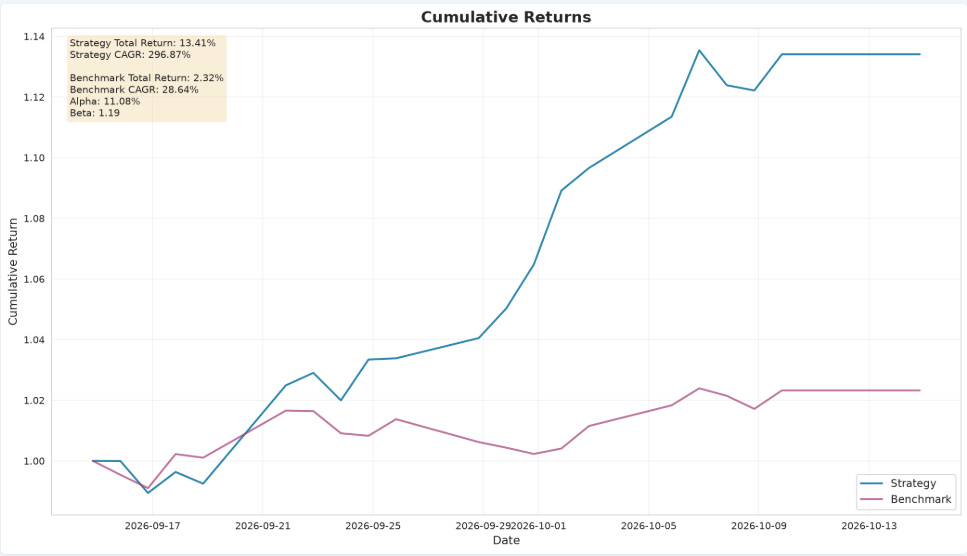
Backtesting: the best performing momentum portfolio over the last month
We perform daily backtesting of our risk-adjusted momentum strategy across 100+ portfolios, built based on combinations of look back parameters and daily trading volume